A deductible determines how much of a covered property loss a homeowner must absorb before an insurer contributes to the claim. Choosing the right homeowners insurance deductible means balancing premium cost against the amount a household could pay after fire, theft, wind, or another insured event. Homeowner’s insurance deductibles, percentage calculations, storm provisions, claims, and emergency savings all deserve attention before a policy is selected. A small percentage on paper can represent thousands of dollars.
- Calculate each deductible in dollars.
- Compare the amount with household savings.
- Read storm provisions apart from other losses.
- Review the choice at renewal.
Choosing Insurance Deductibles
A practical policy review often starts by placing several deductible choices beside the premiums, then calculating what each choice would cost during a claim. That exercise has shown why a $500 deductible and a percentage deductible cannot be compared by appearance alone. The Texas Department of Insurance example uses a home insured for $150,000 and shows that a 5 percent deductible equals $7,500. Homeowner’s insurance becomes much easier to judge once percentages are converted into dollars.
- Write down every offered deductible.
- Convert percentages into dollar amounts.
- Compare the figures with repair scenarios.
How Deductibles Work
The National Association of Insurance Commissioners defines a deductible as the “amount of loss paid by the policyholder before any loss is paid by the insurer.” A homeowner with a $1,000 covered loss and a $300 deductible would receive $700 under the example provided by the Texas Department of Insurance. Homeowner’s insurance may also contain separate deductibles for particular causes of damage.
- Find the dollar deductible.
- Identify cause-specific provisions.
- Check the declarations page.
- Calculate the owner’s share.
Higher Deductible Savings
Raising a deductible usually shifts more loss to the policyholder and can reduce the premium. The NAIC explains that choosing a deductible means accepting the portion of a loss the household feels it can afford, and its guidance lists $500 and $1,000 as examples insurers may offer. Homeowner’s insurance savings should be weighed against that added claim exposure, not viewed as free money.
- Record the annual premium difference.
- Measure added claim responsibility.
- Calculate the break-even period.
- Keep the deductible accessible.
- Avoid choosing from premium alone.
Lower Deductible Tradeoffs
A smaller deductible places less of a covered loss on the homeowner, but the premium may increase. The NAIC states that lower deductibles are associated with higher policy premiums because the insurer begins sharing losses at a reduced threshold. Homeowner’s insurance with this structure may suit a household that prefers paying more through premiums rather than facing a sizable bill after property damage.
- Compare premium increases.
- Consider cash reserves.
- Estimate likely repair expenses.
Percentage Deductible Math
Percentage deductibles require extra attention because they are generally calculated against the home’s insured value rather than the repair bill. The Texas Department of Insurance shows that a 5 percent deductible on $150,000 of insured value equals $7,500, and a $6,500 roof loss in that example would fall below the deductible. Homeowner’s insurance shoppers should perform this calculation before signing paperwork. Five percent can look modest until a dollar sign is attached.
- Locate the dwelling limit.
- Multiply it by the percentage.
- Compare that result with savings.
- Test several loss amounts.
Windstorm Deductible Rules
Wind and hail losses may carry a deductible that differs from the one used for fire, theft, or other covered events. The NAIC explains that windstorm deductibles can apply when wind or hail causes damage, including an event where a tree falls onto a roof. Homeowner’s insurance owners should identify every deductible shown on the declarations page so storm damage does not trigger an unexpected cost.
- Find wind and hail provisions.
- Check trigger language.
- Convert percentages to cash amounts.
- Separate flood risk from wind coverage.
- Keep declarations with insurance records.
Hurricane Deductible Costs
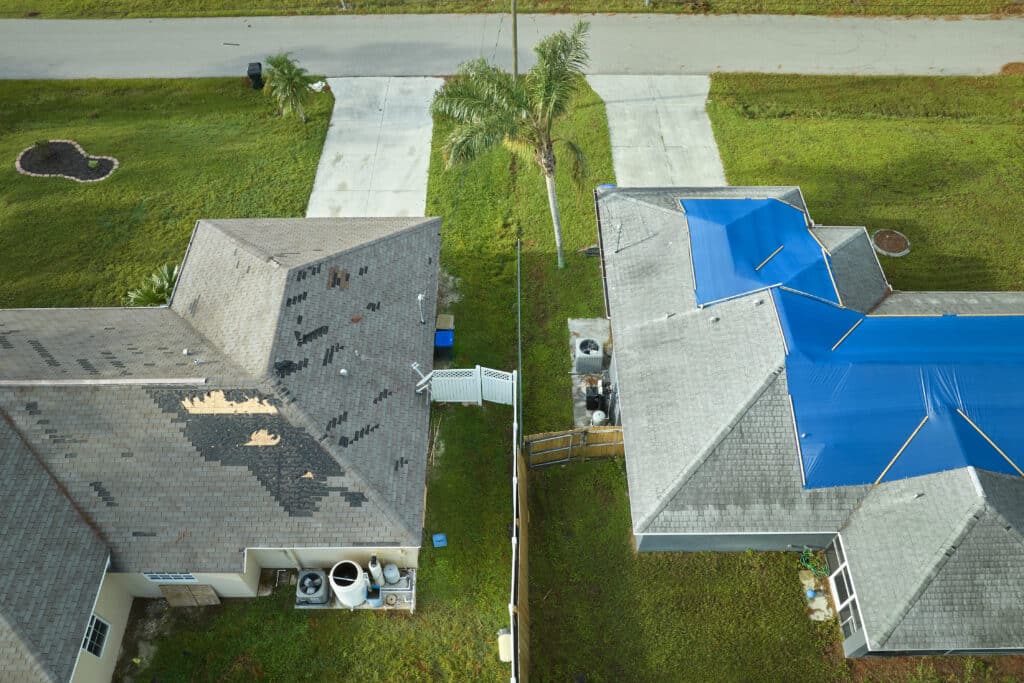
Hurricane and named-storm deductibles can place a substantial share of repairs on a homeowner. The Louisiana Department of Insurance reported in June 2026 that named-storm or hurricane deductibles typically run 2 to 5 percent of insured value, and its example shows a 3 percent deductible on a $200,000 home producing $6,000 in out-of-pocket responsibility. Homeowner’s insurance should be examined using that dollar figure rather than the percentage alone.
- Identify the storm percentage.
- Calculate the dollar obligation.
- Check when the provision activates.
Deductibles And Claims
Small losses can produce little or no insurance payment when repair expenses sit near the deductible. Texas regulators give an example where $6,500 of roof damage falls below a $7,500 deductible, meaning the policy pays nothing toward that repair under the stated facts. Homeowner’s insurance owners still need to follow policy requirements when damage occurs, since reporting duties and claim terms depend on the contract.
- Estimate damage before comparing figures.
- Review claim reporting requirements.
- Document property damage.
- Keep contractor estimates.
Emergency Fund Planning
A deductible works only as well as the homeowner’s ability to fund it when something goes wrong. The NAIC advises consumers choosing a larger deductible to make sure they can afford it after a loss. Homeowner’s insurance planning can include keeping the deductible amount within emergency reserves instead of counting on credit during a stressful repair.
- Match the deductible to savings.
- Keep funds available for repairs.
- Consider simultaneous household expenses.
- Rebuild reserves after using them.
- Avoid selecting an unreachable amount.
Home Value Matters
Percentage deductibles can rise when the insured dwelling amount rises because the percentage is applied to that coverage value. NAIC guidance states that percentage deductibles are typically applied to the home’s insured value to determine the amount owed by the policyholder. A homeowner’s insurance renewal that increases dwelling coverage can therefore change the deductible in dollars even when the stated percentage stays unchanged.
- Recalculate after coverage increases.
- Check changes following renovations.
- Do not rely on last year’s dollar figure.
Comparing Policy Deductibles
Policy comparisons work better when quotes use matching deductibles, coverage limits, and loss provisions. One carrier may quote a tempting premium while assigning more storm risk to the homeowner, another may cost more yet require less cash after a covered loss. Homeowner’s insurance decisions should compare both sides of that equation. Price tells only part of the story.
- Match dwelling limits.
- Compare ordinary deductibles.
- List wind provisions.
- Calculate hurricane percentages.
- Review coverage differences.
Reviewing Deductibles Yearly
A deductible selected years ago may no longer fit household finances or current dwelling coverage. The Texas Department of Insurance says the declarations page lists coverage, limits, and deductibles, making it a useful place to begin a renewal review. Homeowner’s insurance should be checked after income changes, remodeling, coverage increases, or adjustments to emergency savings.
- Read each renewal declaration.
- Recalculate percentage amounts.
- Compare savings with exposure.
- Check storm deductible changes.
Balancing Cost And Risk
The right deductible sits where premium savings and claim responsibility meet household finances. Larger deductibles can reduce policy cost, while reduced deductibles limit the cash required after a loss, and percentage provisions can create a much bigger obligation than their numbers first suggest. Homeowner’s insurance works better when a family calculates these outcomes before damage occurs. The goal is not the smallest premium, it is a deductible the household can actually handle.
- Know every deductible.
- Translate percentages into dollars.
- Compare the result with reserves.
- Review the balance each year.
Homeowner’s Insurance Key Takeaways
Homeowner’s insurance deductible choices affect both premium costs and the amount retained by the household during a covered claim. Regulators advise consumers to understand the dollar value of percentage deductibles, check separate storm provisions, and select an amount they can afford after a loss. A few calculations can reveal far more than the percentage printed on the declarations page.
- A deductible is the homeowner’s share of a covered loss.
- Increasing it can reduce premium costs.
- Percentage deductibles use the insured dwelling value.
- Storm losses may use separate provisions.
- Emergency savings should support the chosen amount.
FAQs
What Deductible Is Best?
No single deductible fits every household because savings, coverage amounts, property risks, and budgets differ. The NAIC recommends choosing an amount the policyholder can afford to bear after a loss. Homeowner’s insurance owners can compare several options by calculating both premium savings and claim responsibility.
Does Deductible Affect Premium?
Yes. The NAIC explains that a lower deductible generally carries a higher premium, while accepting more of a loss can reduce policy cost. The savings need to be compared with the added amount a homeowner would owe during a claim.
Are Hurricane Deductibles Separate?
They can be. The NAIC says hurricane or named-storm deductibles may apply separately from the deductible used for other insured perils and can be expressed as a dollar figure or percentage. Policy triggers and state rules determine when those provisions apply.
Can Deductibles Be Changed?
Insurers may offer deductible choices, and renewal is a practical time to ask what options are available. A change can affect premium cost and the amount owed during a covered loss. Homeowner’s insurance owners should compare the new dollar exposure before accepting a revised deductible.
Should Homeowners Choose Higher?
A larger deductible can make sense when the premium savings justify the added risk and the household has enough accessible money to cover a claim. The NAIC specifically advises consumers to make sure they can afford the deductible they select. A lower premium has little value if the deductible creates a repair bill the household cannot fund.
- About the Author
- Latest Posts
With over 80 years of combined experience, Southern Ambit Insurance stands as an authority in simplifying the complex world of insurance. Our team is committed to providing exceptional customer service, conducting thorough risk assessments, and crafting tailored policies that offer our clients the best protection and peace of mind.